
Private equity secondaries have moved from a niche liquidity solution to a core portfolio-building tool. In our recent white paper on private equity secondaries, we examined why: mature assets, reduced blind-pool risk, earlier cash flows, discounted entry opportunities and a fundamentally different return pattern from traditional primary private equity.
But not all secondary strategies produce those outcomes in the same way.
Our recent analysis of StepStone Private Equity Strategies Fund (STPEX) provides a particularly interesting example. What stands out is not simply the fund’s secondary exposure. It is the infrastructure surrounding it.
Scale that can actually improve the economics
Large investment organizations normally come with an obvious trade-off: more infrastructure, more people and potentially more cost.
StepStone presents an interesting counterexample.
In our discussion with StepStone, the firm described a broader platform deploying approximately $75 billion annually across private markets. That matters because STPEX does not have to build its investment pipeline independently.
StepStone is continuously deploying primary capital, evaluating managers, participating in co-investments and executing secondary transactions. That creates a persistent flow of opportunities through the same platform.
For an evergreen secondary vehicle, this can have a direct economic benefit.
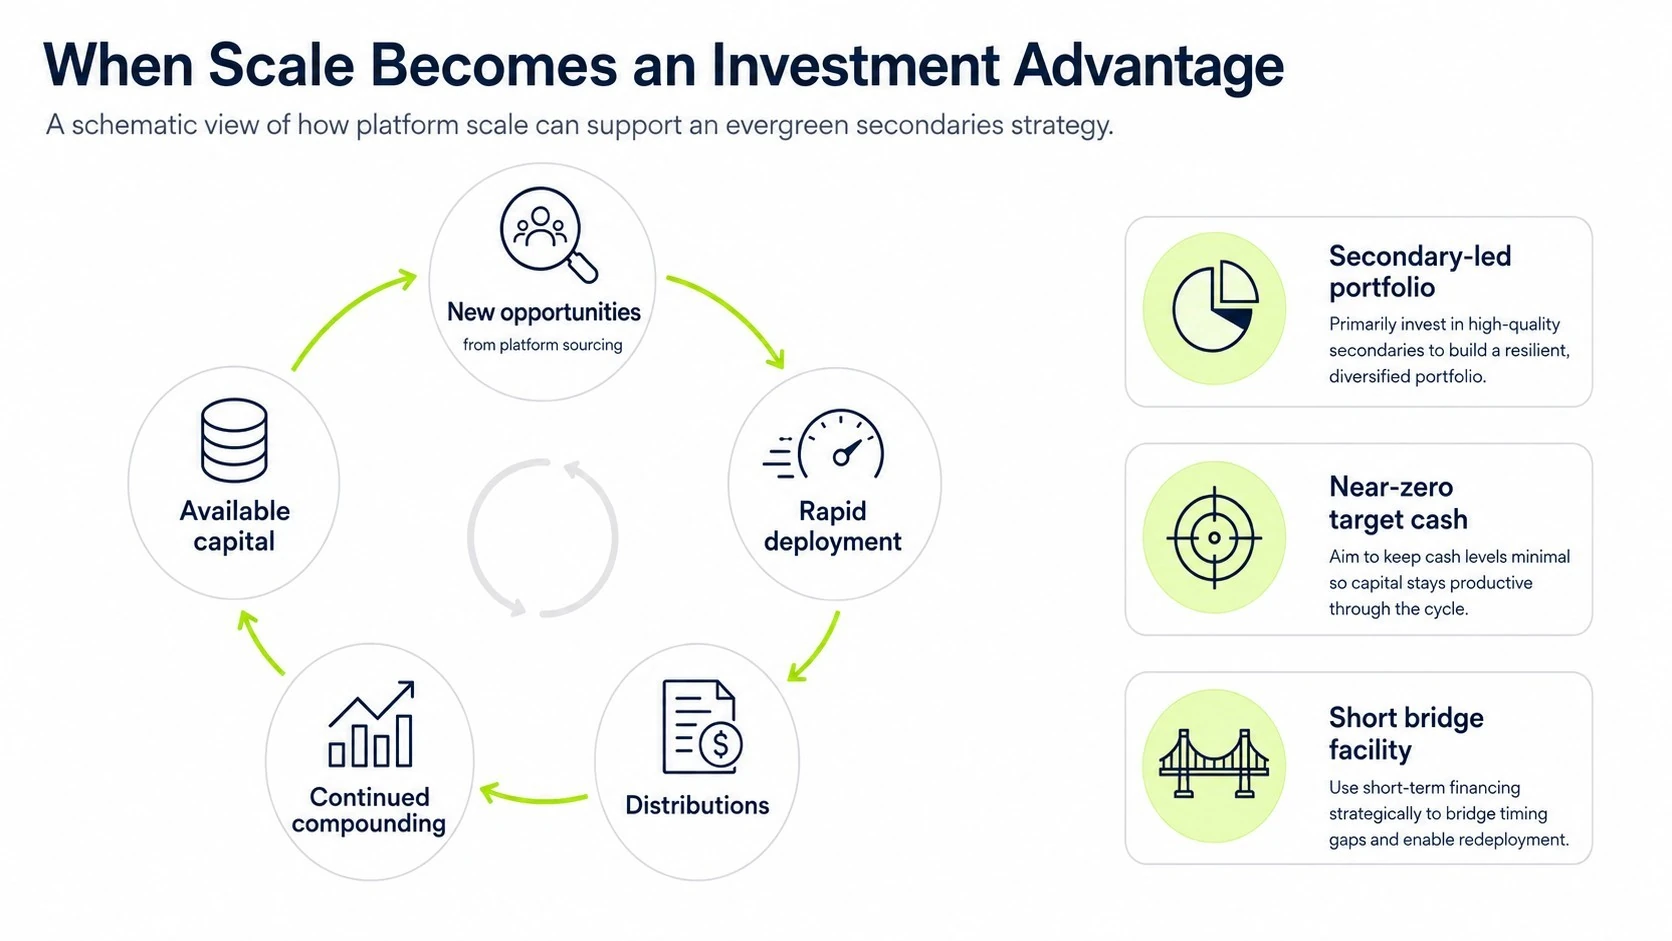
Distributions → available capital → new opportunities → rapid redeployment → continued compounding
The shorter the period between receiving capital and putting it back to work, the less return is lost to idle cash.
Scale, in this case, can become an investment mechanism.
A portfolio designed to stay invested
That became even clearer when we discussed liquidity.
STPEX currently consists overwhelmingly of secondary investments—approximately 91% secondaries and 9% co-investments, with only minimal seasoned-primary exposure, according to our conversation with StepStone.
Within the secondary portfolio, LP-led transactions remain dominant, with GP-led exposure currently around 19%.
But perhaps the more interesting number is the fund’s target cash position: as close to zero as practical.
That is very different from maintaining a permanent 5%–10% liquidity reserve.
STPEX instead seeks to generate liquidity from the underlying portfolio itself. Mature secondary assets generate realizations and distributions, while a credit facility can bridge short timing differences when necessary.
The fund provides 5% semiannual repurchase capacity, but that capacity should not be confused with an assumption that 5% of investors redeem every six months.
This distinction became important in our modeling.
Liquidity is not simply the amount of cash sitting on the balance sheet. It is the portfolio’s capacity to generate and access cash when required.
The StepStone sourcing advantage
There is another dimension to scale.
A manager deploying significant primary capital can approach a GP from several directions. It may already be an LP in the manager’s funds, have evaluated its portfolio companies, participate in co-investments and simultaneously provide secondary liquidity.
That creates information and sourcing advantages that a secondary-only buyer may not possess.
StepStone executives described this to us less as a broad “buy everything” approach and more as selecting specific opportunities from a very large pipeline.
The distinction matters.
The economic objective is not simply: buy at the largest discount.
It is closer to:
identify attractive assets → find the best structure through which to own them → negotiate attractive entry economics → remain invested through realization.
Discount capture remains important. But it is one part of a broader acquisition and portfolio-construction process.
Historical return is not the same as expected return
This distinction also changed our modeling.
StepStone’s older evergreen private-markets vehicle, SPRIM, has reported exceptionally strong historical performance. But historical performance—particularly over a favorable period for secondary acquisitions—should not automatically become a ten-year portfolio assumption.
In our discussion, StepStone indicated a 14%–15% net annual return target for STPEX, while noting that current performance has been running above that level.
We therefore separate three concepts:
Historical observed return — what a manager actually achieved.
Forward expected return — the assumption used for long-term portfolio planning.
Scenario return — what may occur when markets, valuations, exits and liquidity behave differently from the base case.
For STPEX, our current forward modeling anchor is 14.5% net, the midpoint of the manager-indicated range.
That is considerably more conservative than simply extrapolating recent historical performance.
The return engine
Our research suggests that STPEX’s return mechanism can be understood through five principal economic contributors:
Underlying company growth.
The companies inside acquired funds continue to grow, generate cash flow and potentially deleverage.
Acquisition economics.
LP interests and other secondary assets may be acquired at attractive prices, creating value at entry.
Valuation change.
Changes in valuation multiples and subsequent portfolio marks can add—or subtract—value.
Investment income.
Mature assets can generate dividends, interest and other recurring cash flows.
Exit realization.
Assets ultimately convert NAV into realized proceeds, sometimes above their prior carrying values.
The precise contribution of each factor is uncertain. What matters for portfolio analysis is that they behave differently across economic environments.
That is where modeling becomes useful.
Secondaries are not interchangeable
Our work across StepStone, Pomona, HarbourVest, Coller and other secondary strategies has reinforced an important conclusion:
“Private equity secondaries” is not a single investment.
Managers differ in sourcing, transaction mix, portfolio maturity, GP-led exposure, liquidity architecture, cash management, reinvestment speed, underwriting and portfolio construction.
One manager may provide stronger diversification. Another may emphasize downside protection. Another may have particularly strong GP-led capabilities. StepStone’s platform appears especially differentiated by the combination of scale, primary-manager relationships, transaction access and rapid capital redeployment.
None of those characteristics makes one fund universally superior.
The relevant question is: What does this particular secondary strategy do when inserted into this particular investor portfolio?
That is the question our portfolio modeling framework is designed to answer.
What the modeling shows
Using a 14.5% forward net return assumption and integrating a 20% STPEX allocation into our representative public-market Core portfolio, the deterministic model increases the expected ten-year portfolio outcome relative to Core alone.
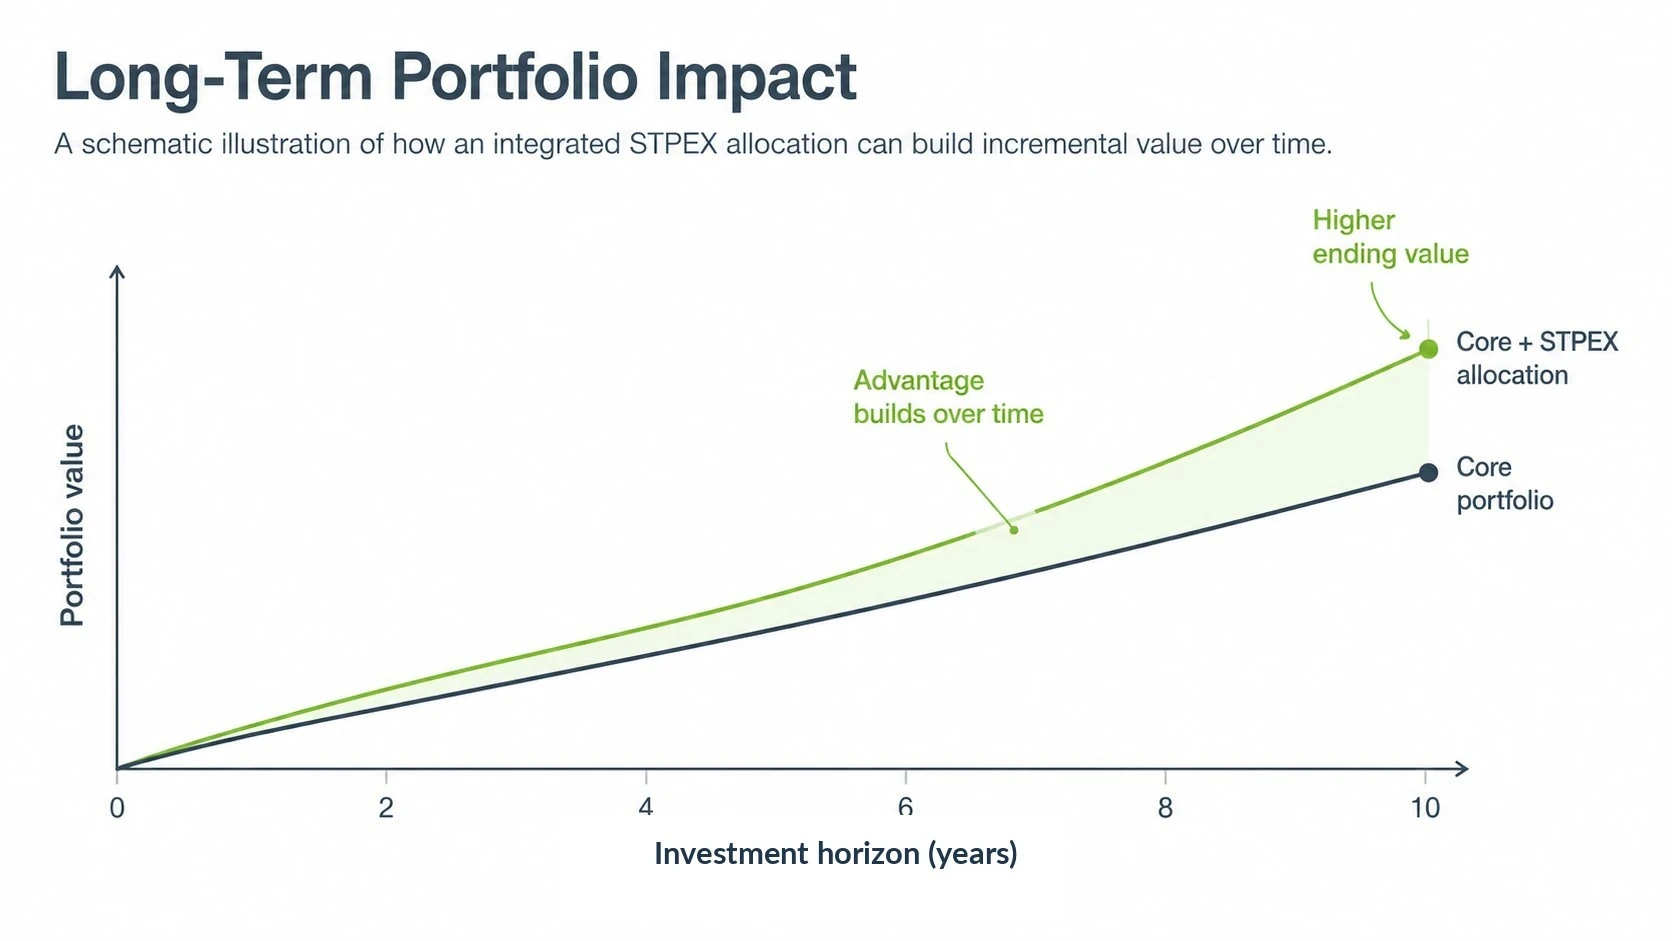
But deterministic return is only the starting point.
Our current Monte Carlo framework models public and private assets together across 10,000 paths and 40 quarterly periods, allowing economic regimes, impairments, exit delays, liquidity conditions and valuation changes to evolve jointly rather than comparing private markets against a fixed public-market return.
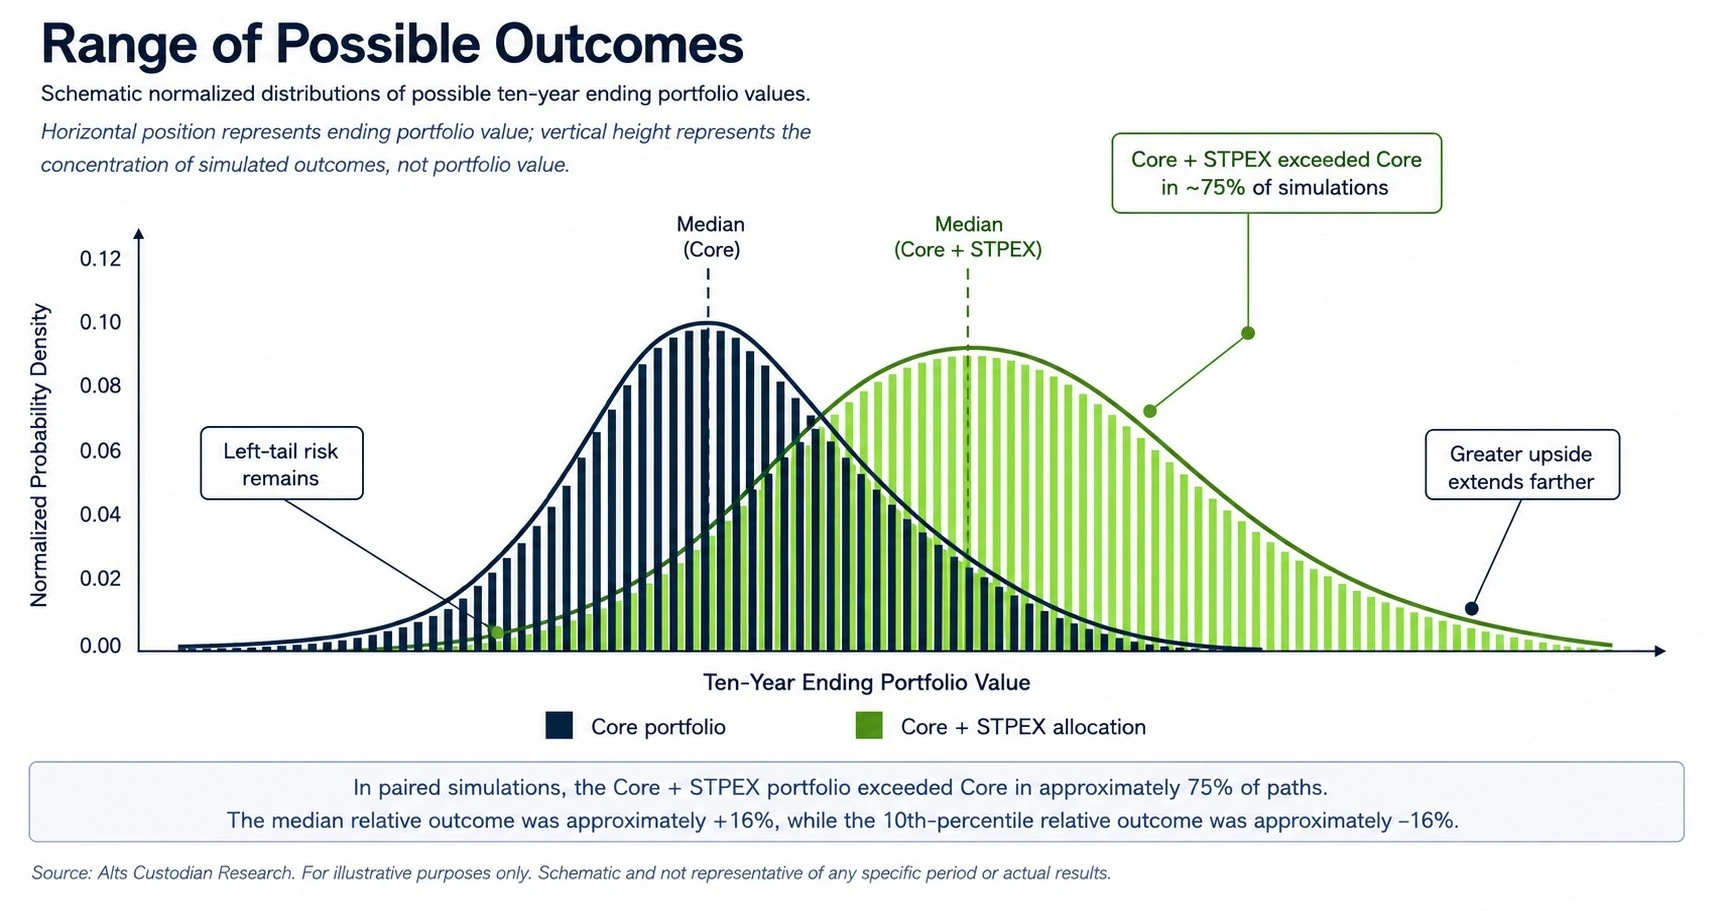
Under the current calibration, the portfolio containing a 20% STPEX allocation outperformed the public Core portfolio in approximately 75% of simulated ten-year paths.
Importantly, it did not win in all of them.
The 10th-percentile relative outcome was approximately −16%, while the median relative outcome was approximately +16%. That range is precisely why we believe probability distributions are more useful than a single expected-return number.
Structural stress testing goes one step further.
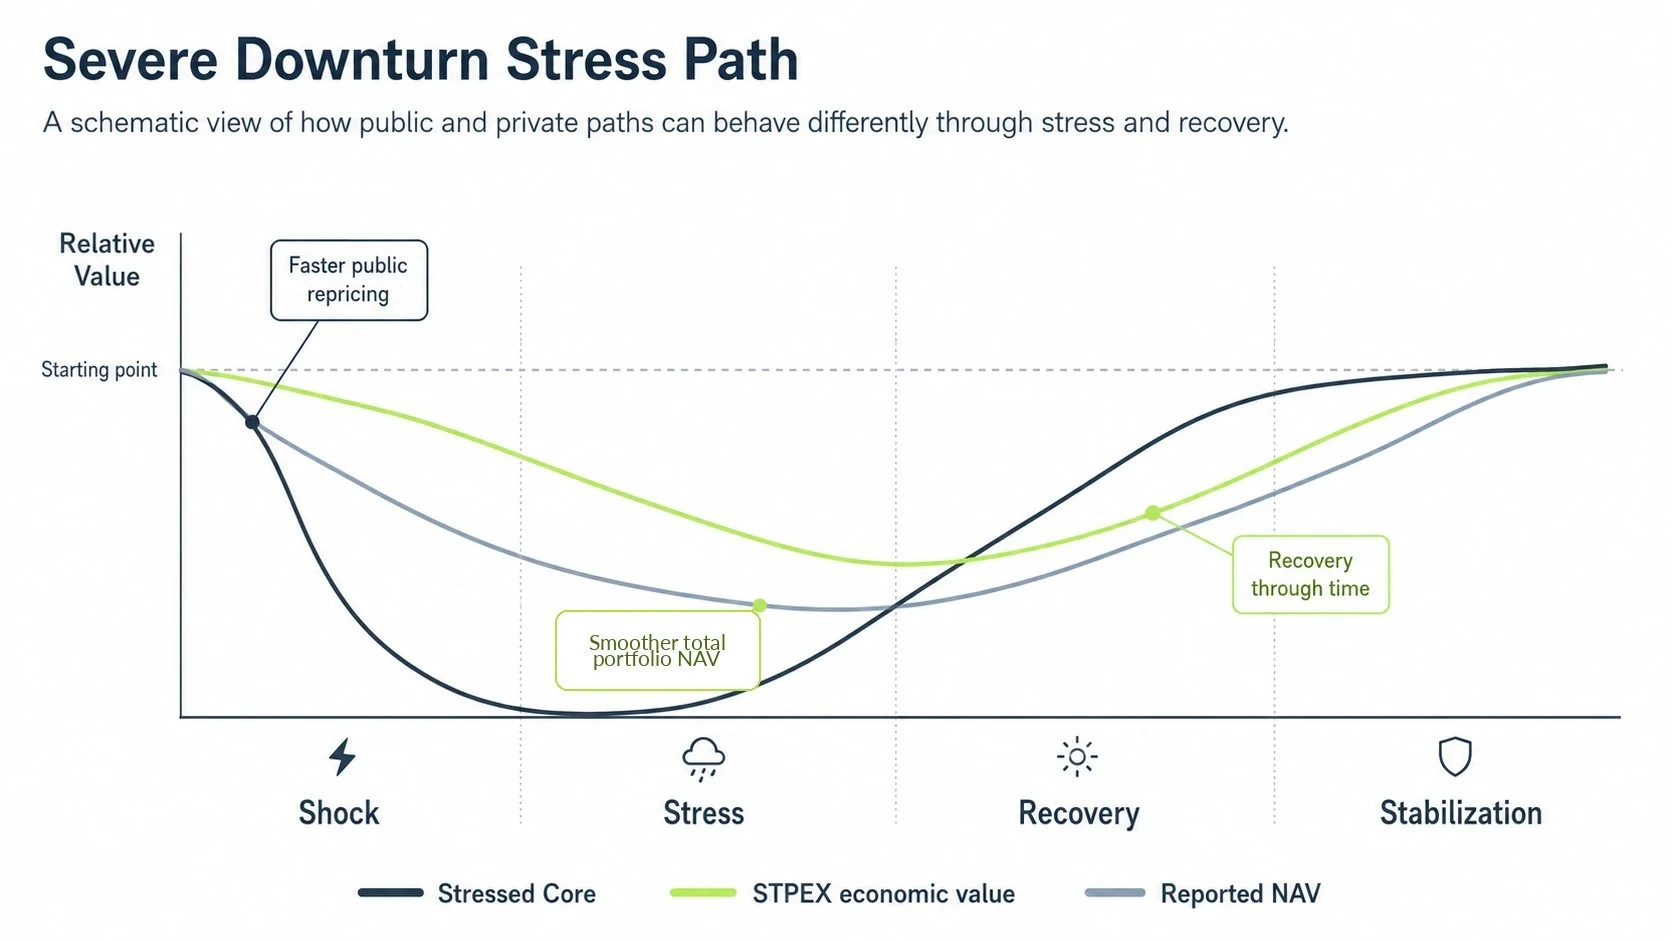
We separately test events such as valuation markdowns, impairment, delayed exits, reduced distributions, acquisition-price compression, interrupted reinvestment and credit-facility constraints. Public markets reprice faster and more deeply; private economic deterioration occurs later; and reported NAV adjusts more gradually. In the governed combined severe-stress path, the integrated portfolio retains a long-term advantage, while stress reduces the normal-case advantage. The diversification benefit is meaningful, but certainly not unconditional.
The broader conclusion
Secondaries can improve portfolio construction through more than return.
They can alter:
- timing of cash flows,
- deployment efficiency,
- diversification,
- downside behavior,
- recovery patterns,
- and dependence on public-market outcomes.
StepStone is an especially useful case study because its scale appears to influence several of those variables simultaneously.
But the larger lesson is not that every portfolio should own STPEX—or any other secondary fund.
It is that selecting an alternative investment without modeling how its specific economic characteristics interact with the existing portfolio leaves out much of the information that matters.
The manager matters. The structure matters. The portfolio it enters matters even more.
This article is for educational purposes only and should not be considered investment, tax, legal, or accounting advice. The figures are schematic illustrations and do not present confidential advisor-model outputs.